How to Document Your High-Value Home for Insurance Purposes in New Mexico
When something goes wrong — a wildfire sweeps through the East Mountains, a pipe bursts in your Santa Fe adobe, or a theft hits your Albuquerque estate — the quality of your insurance claim payout often comes down to one thing: documentation. For high-value homeowners, the gap between what an insurer offers and what you actually need to rebuild can be enormous if you haven't done this work in advance. This guide walks you through exactly how to document your property, finishes, and possessions so you're fully protected when it matters most.
Why Documentation Is Especially Critical for High-Value Homes in New Mexico
Standard homeowners insurance is designed around average homes. High-value properties — think custom adobe architecture in Santa Fe, hillside estates in the Sandia foothills, or luxury builds in Rio Rancho's gated communities — have finishes, materials, and craftsmanship that don't appear on any standard pricing formula. Insurers set initial valuations based on square footage and general construction type. Without documentation proving exactly what you have, adjusters default to generic replacement estimates that can fall dramatically short.
Consider a hand-plastered Venetian interior, reclaimed vigas from a 200-year-old structure, or a custom kitchen with hand-painted Talavera tile work. None of these have a line item in a standard claims database. If you can't prove they existed and what they cost, you likely won't be paid to restore them. This is why specialized insurers like Chubb, who cater specifically to high-value properties, strongly recommend comprehensive home documentation as part of onboarding any new policy.
Beyond finishes, New Mexico's wildfire risk adds urgency. With approximately 55% of buildings in Albuquerque facing significant wildfire exposure, a total loss is a realistic scenario — not just a theoretical one. Understanding how guaranteed replacement cost luxury home New Mexico policies work is a critical companion to proper documentation, because that coverage only pays out fully when your insurer can verify what they're replacing.
Step 1: Build a Comprehensive Home Inventory
A home inventory is a detailed record of everything inside and structurally significant about your property. For high-value homeowners, this goes well beyond a simple list of appliances.
What to Include
- Structural and architectural features: Custom millwork, ceiling heights, flooring materials (wide-plank hardwood, imported stone, hand-set tile), built-in cabinetry, fireplaces, and specialty plaster or stucco finishes
- Major systems: Smart home technology, solar arrays, whole-home generators, custom HVAC, and home theater or automation systems
- Art, collectibles, and jewelry: Itemized with purchase receipts, auction records, or provenance documentation
- High-end appliances and fixtures: Brand, model, purchase price, and installation date
- Outdoor features: Pools, outdoor kitchens, custom landscaping, and detached structures
Use a spreadsheet or a dedicated home inventory app (several insurers provide their own) to log each item with a description, estimated value, purchase date, and serial number where applicable. Store this file in cloud storage and keep a copy offsite or in a fireproof safe — not just on a local hard drive that could be destroyed in the same event you're filing a claim over.
Step 2: Photograph and Video Every Room and Detail
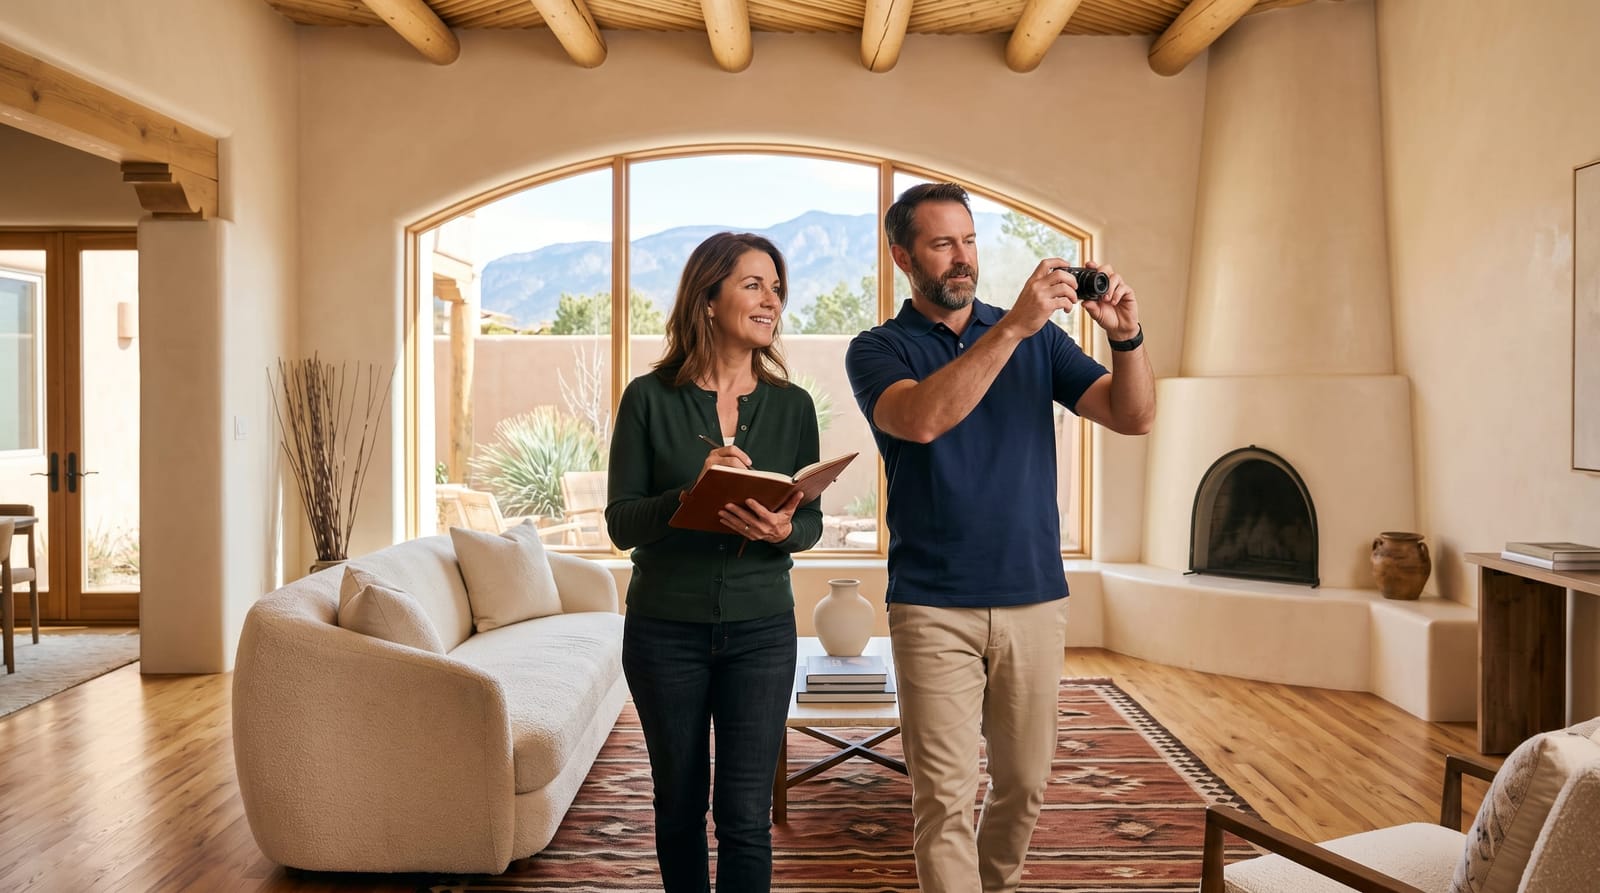
Documentation without visual evidence is far weaker than documentation with it. A thorough photo and video record is one of the most powerful tools you have in a disputed or complex claim.
How to Do This Effectively
- Shoot every room from multiple angles, including corners, ceilings, and floors. Don't skip closets, utility rooms, or garages.
- Get close-up shots of custom finishes — hand-carved wood details, custom tile patterns, specialty hardware, and decorative plasterwork. These are the elements most likely to be undervalued without proof.
- Film a continuous walkthrough video narrating what you're showing. Spoken context ("this is the original reclaimed wood ceiling in the primary bedroom, installed in 2019 at a cost of approximately $28,000") adds a layer of detail that photos alone can't provide.
- Photograph serial numbers on electronics, appliances, and equipment.
- Date-stamp everything and store files in a timestamped folder so there's no question of when the record was created.
Update your visual documentation every one to two years, and after any significant renovation or purchase. A remodel that adds a wine cellar or a home gym is a documentation event, not just a construction project.
Step 3: Get Professional Appraisals for Custom Finishes and Specialty Items
Photography shows that something exists. Appraisals establish what it's worth. For high-value homes, professional appraisals are not optional — they are essential.
When to Hire an Appraiser
- At the time of purchase for any property with significant custom or historic elements
- After major renovations that add or upgrade finishes
- Every three to five years for fine art, jewelry, wine collections, and antiques, as market values shift
- Before adding a scheduled personal property rider to your policy
In New Mexico, where Santa Fe and Taos properties often include authentic Native American art, historic adobe construction, or significant antique furniture, specialized appraisers who understand regional markets are worth seeking out. Generalist appraisers may undervalue items that have strong regional or cultural significance. Keep original appraisal reports, updated appraisals, purchase receipts, and any certificates of authenticity in your documentation file alongside your inventory and photographs.
Step 4: Organize and Maintain Your Records for Insurer Access
The most thorough documentation in the world is useless if you can't access it quickly after a loss or if it wasn't shared with your insurer before a claim. Organization matters as much as completeness.
Best Practices for Record Maintenance
- Create a master policy document that summarizes your coverage limits, scheduled items, and riders in plain language alongside your inventory
- Share your documentation with your insurance agent annually so coverage limits can be adjusted to reflect current values — particularly important as construction costs and market values in Albuquerque, Santa Fe, and Rio Rancho have risen significantly in recent years
- Use a three-location rule: store records at home (fireproof safe), in cloud storage, and with a trusted party such as your attorney or a safety deposit box
- Keep contractor invoices and permits for every renovation, which serve as both proof of what was done and evidence of legitimate cost
- Review your documentation when you review your policy — make it an annual habit, ideally at renewal time
High-value insurers like Chubb often offer concierge-style services that include risk assessment visits and can help identify documentation gaps before they become claims problems. If your insurer offers this, take advantage of it.
Frequently Asked Questions
How often should I update my home inventory?
Update your home inventory at least once a year and immediately after any significant purchase, renovation, or acquisition. An outdated inventory is one of the most common reasons high-value homeowners receive insufficient claim payouts. Annual policy renewal is a natural trigger point to review and refresh your records.
Do I need a separate appraisal for every piece of art or jewelry?
For items valued above $5,000 to $10,000, a standalone appraisal from a certified specialist is strongly recommended. For collections of lower-value items, a grouped appraisal covering the collection as a whole may be sufficient. Confirm thresholds and documentation requirements directly with your insurer, as they vary by policy type and carrier.
What if I didn't document something before it was lost or damaged?
Without documentation, you'll rely on adjuster estimates, contractor quotes, and any surviving records such as bank statements, credit card receipts, or contractor invoices. This is why proactive documentation matters — retroactive proof is much harder to establish, particularly for custom finishes unique to your home. Some insurers will consider testimony from contractors familiar with the work, but this is never as strong as contemporaneous records.
Will my insurer use my documentation directly when processing a claim?
Yes — a well-organized documentation file can significantly accelerate claims processing and reduce disputes over replacement values. Premium carriers who specialize in high-value homes are generally more receptive to detailed documentation as the basis for settlement. Always submit your inventory and appraisals directly to your insurer and keep copies of everything you provide them.
Protecting Your Home Starts Before the Claim
Thorough documentation is one of the most impactful things a high-value homeowner can do outside of choosing the right policy. In New Mexico — where wildfire risk, custom construction, and regional artisanship create a uniquely complex insurance landscape — there is no substitute for organized, detailed records. Pair strong documentation with the right coverage structure, including understanding options like guaranteed replacement cost for luxury homes in New Mexico, and you put yourself in the strongest possible position when a claim arises. Start documenting now, before you ever need it.