Homeowners Insurance in Santa Fe, New Mexico: Protecting Your Home in the City Different
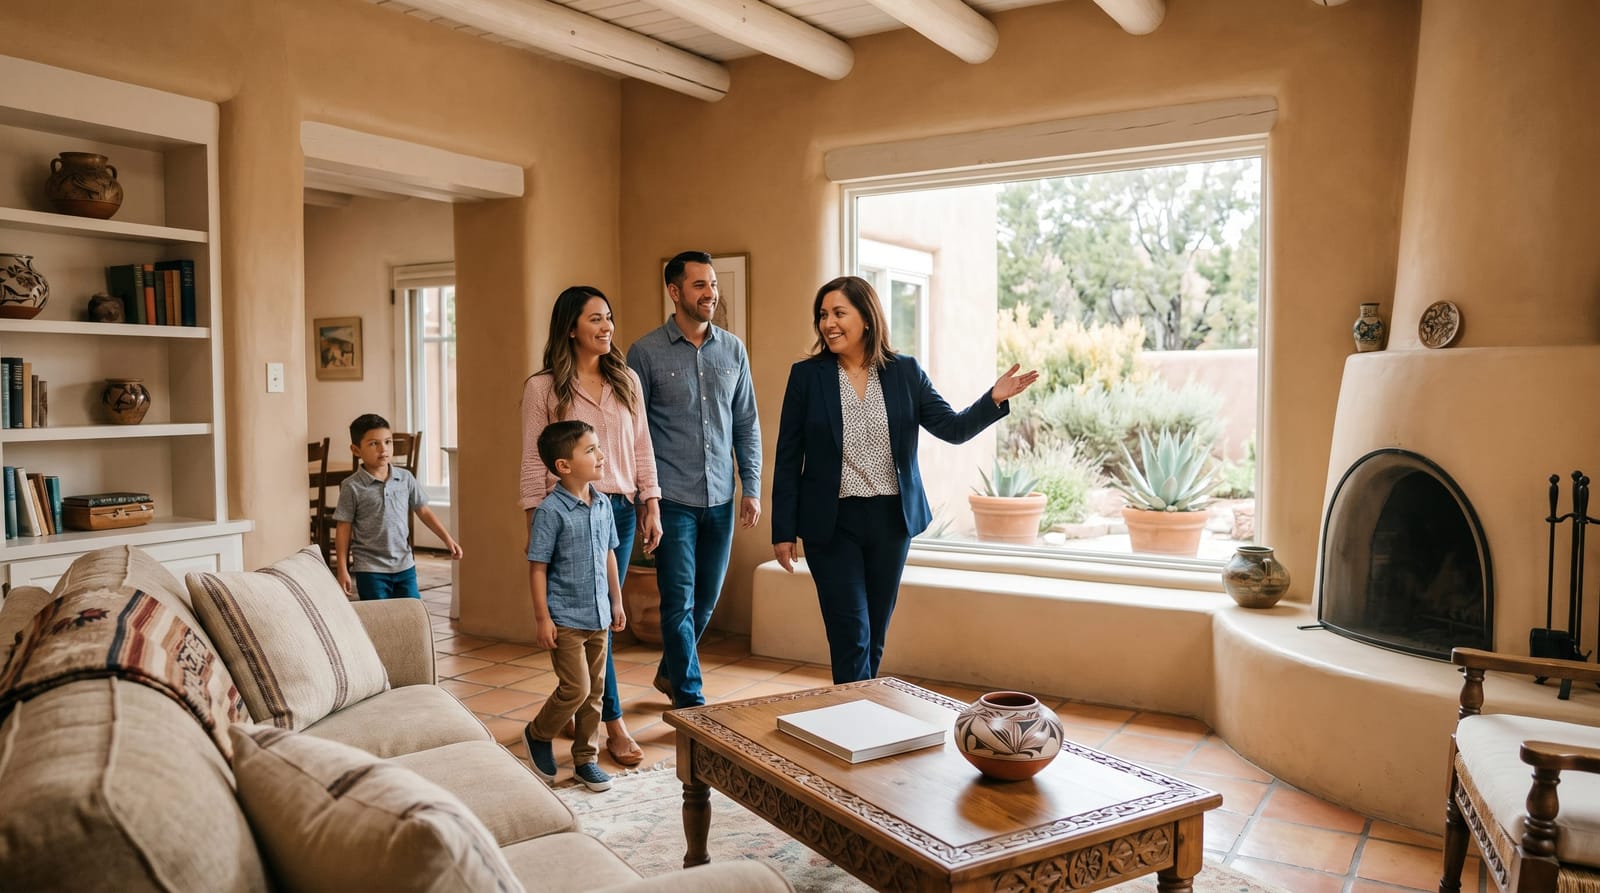
Santa Fe is unlike anywhere else in New Mexico — and that means insuring a home here comes with its own set of considerations. Whether you own a historic adobe in the Canyon Road neighborhood, a pueblo-style estate in the foothills, or a modern luxury home near the ski basin, finding the right homeowners insurance in Santa Fe, New Mexico requires more than a standard policy. This guide walks you through the key factors that shape coverage in Santa Fe, from wildfire exposure and high-value construction to fine art and luxury personal property. If you're comparing options or reviewing your current coverage, this post gives you the local context you need. We also cover how Santa Fe's insurance landscape fits into the broader picture of homeowners insurance across New Mexico.
What Makes Santa Fe Different for Home Insurance
Santa Fe has a well-earned reputation as a cultural capital. It also has a home market unlike any other in New Mexico. Many properties here are genuinely irreplaceable. Adobe construction, hand-carved vigas, historically significant architecture, and custom craftsmanship all contribute to homes that can be expensive — and sometimes complicated — to insure properly.
The average cost of homeowners insurance in Santa Fe, New Mexico is around $2,225 per year. That puts the city close to the state average, but that number can vary significantly depending on your home's location, construction type, age, and value.
Homes in the $500,000 to $2 million range are common here. When coverage limits need to reflect that kind of value, a standard off-the-shelf policy often falls short. Here's what sets Santa Fe apart:
- Historic and pueblo-style construction that costs more to repair or rebuild than conventional framing
- Wildfire exposure in the foothills, mountains, and outlying neighborhoods
- High-value personal property including fine art, jewelry, and antiques
- Upscale neighborhoods where replacement cost values require higher coverage limits
- Proximity to forest land that affects insurer availability in some zip codes
Getting coverage right means understanding all of these factors — not just picking a policy based on price alone.
Wildfire Risk in Santa Fe and What It Means for Coverage
Wildfire is a real concern for many Santa Fe homeowners, especially those living near the Sangre de Cristo Mountains or in neighborhoods that border open land. The foothills east of the city, areas near Hyde Memorial State Park, and communities along the mountain road corridor all carry elevated wildfire exposure.
As wildfires have become more frequent across the West, insurance companies have responded by reassessing risk in affected areas. Some carriers have become more selective. Others have raised rates for properties in high-risk zones. A few have reduced their presence in certain New Mexico markets altogether.
What Wildfire Risk Means for Your Policy
Higher wildfire risk can affect your coverage in several ways:
- Some insurers may decline to write new policies in certain zip codes
- Premiums may be higher for homes in fire-prone areas
- You may be required to meet specific defensible space or fire-hardening requirements
- Certain older policies may not include adequate dwelling replacement cost coverage
Working with a local agency matters here. A local agent knows which carriers are actively writing policies in Santa Fe's higher-risk zones and which ones offer competitive rates without sacrificing coverage quality. If you're also looking at coverage in nearby mountain communities, our post on home insurance in Taos, New Mexico covers similar terrain and wildfire considerations for historic and high-value mountain properties.
Steps to Protect Your Home and Your Coverage
Maintaining defensible space around your property is one of the most important things you can do. It reduces fire risk and can help you qualify for better rates. Creating at least 30 feet of cleared, well-maintained space around your structure is a widely recommended starting point. Some insurers look favorably on additional steps like ember-resistant vents, metal roofing, and fire-resistant landscaping.
Insuring Historic Adobe and Pueblo-Style Homes
Adobe homes are one of Santa Fe's defining features. They are also some of the most challenging properties to insure correctly. Standard homeowners policies are often built around conventional wood-frame construction. Adobe and pueblo-style homes require a different approach.
The core issue is replacement cost. If your home were damaged and needed to be rebuilt, the cost of replicating original adobe construction — hand-plastered walls, traditional vigas and latillas, custom tile work, and historic details — can be substantially higher than what a generic policy would cover.
Key Coverage Considerations for Adobe Homes
- Extended replacement cost coverage: This pays beyond your stated dwelling limit if rebuild costs exceed initial estimates. It provides a meaningful safety net for homes with custom construction.
- Guaranteed replacement cost: Some carriers offer this for qualifying properties. It covers the full cost to rebuild regardless of the limit on your policy.
- Accurate replacement cost appraisal: A professional appraisal that reflects the true cost of rebuilding your specific home is essential. Many homeowners are underinsured simply because their coverage limit was set too low at the time of purchase.
- Ordinance or law coverage: Older homes may need to meet updated building codes during repairs. This coverage helps pay for those required upgrades.
If you own a designated historic property, there may be additional restrictions on how your home can be repaired. That can increase costs further and makes it even more important to have coverage that accounts for the real scope of what rebuilding would involve.
High-Value Personal Property: Art, Jewelry, and Collectibles
Santa Fe is one of the most active art markets in the country. Many homeowners here have invested significantly in original paintings, sculptures, Native American pottery, jewelry, and other collectibles. A standard homeowners policy typically includes personal property coverage — but that coverage has limits.
Most policies cap reimbursement for specific categories of valuables. Jewelry, for example, might have a sublimit of $1,500 to $2,500 per item. Fine art may receive little or no specialized protection under a base policy. For Santa Fe homeowners, those limits can fall well short of the actual value of what's inside the home.
Scheduled Personal Property Coverage
The solution is to schedule high-value items individually. A scheduled personal property endorsement — sometimes called a floater — lists specific items with their appraised values. This provides broader protection than a standard policy sublimit. It often covers accidental breakage and mysterious disappearance, not just theft or fire.
To add scheduled coverage, you'll typically need a recent appraisal for each item. Keeping an updated home inventory with photos and appraisals is a smart habit for any Santa Fe homeowner with meaningful collections. Many insurance professionals recommend reviewing valuations every few years, since art and collectibles can appreciate over time.
Coverage Levels for Santa Fe's Upscale Neighborhoods
Neighborhoods like Las Campanas, Nava Ade, Tierra Contenta's upper sections, and the historic Eastside command some of the highest home values in New Mexico. When homes are valued at $700,000, $1 million, or more, the stakes of being underinsured are significant.
Here's a practical way to think about it. If your home is insured for $400,000 but the actual cost to rebuild it is $700,000, you're exposed to a $300,000 gap. That gap doesn't show up until you need to file a major claim — at which point it's too late to fix it.
What High-Value Home Coverage Should Include
- Dwelling coverage that reflects the actual rebuild cost, not the market value or purchase price
- Other structures coverage for casitas, guesthouses, garages, and walls — common on larger Santa Fe properties
- Loss of use coverage sufficient to cover extended displacement if your home requires significant repairs
- Liability coverage appropriate for higher-value households, including umbrella policy options
- Water backup coverage as an add-on, since this is not included in most standard policies
It's worth noting that Los Alamos — just about 35 miles from Santa Fe — faces similar challenges with high-value homes in elevated-risk terrain. If you're also considering coverage in that area, our guide to homeowners insurance in Los Alamos, New Mexico goes into detail about those specific challenges.
Working With a Local Agent in Santa Fe
Online insurance quotes are easy to get. But for a home in Santa Fe, easy isn't always enough. The combination of unique construction, wildfire exposure, and high property values means that the details of your policy matter more than the speed of getting it.
A local agent who knows Santa Fe can do things a national call center can't. They can help you find carriers that actively write coverage in mountain-adjacent neighborhoods. They can review your current policy limits against your home's actual replacement cost. They understand the difference between a conventional home and a hand-built adobe — and why that difference matters when coverage is being placed.
If you're also exploring coverage in other parts of the state, you may find our guide to homeowners insurance in Albuquerque, New Mexico useful for comparison. For homeowners in smaller northern New Mexico communities, our post on home insurance in Las Vegas, Española, and Northern New Mexico addresses the specific conditions and coverage options in those areas.
Related Coverage Topics for Santa Fe Homeowners
Depending on your property and situation, there are several related topics worth exploring as part of a complete coverage review:
- Wildfire recovery and post-disaster coverage: For those concerned about how claims are handled after a major fire, our post on homeowners insurance in Ruidoso, New Mexico after wildfires offers insight into post-disaster coverage realities that apply broadly across New Mexico.
- Umbrella liability policies: For homeowners with significant assets, an umbrella policy extends liability protection beyond your base homeowners coverage.
- Flood insurance: Flash flooding can occur in Santa Fe and surrounding areas. Standard homeowners policies do not cover flood damage. A separate flood policy through the National Flood Insurance Program or a private carrier may be worth considering.
Getting the Right Homeowners Insurance in Santa Fe, New Mexico
Santa Fe homes deserve coverage as distinctive as the city itself. Whether your property is a centuries-old adobe near the Plaza or a custom-built estate in the hills, the right policy starts with understanding what makes your home unique — and making sure your coverage reflects that reality.
At Quezada Jacobs, we work with Santa Fe homeowners to find coverage that actually fits. We know the local landscape, we know which carriers are strong in this market, and we take the time to understand your home before recommending a policy. If you'd like a personalized review of your current coverage or a new quote, we'd be glad to help. Reach out to our team today and let's make sure your home — and everything in it — is properly protected.